23 Feb

Residential Market Commentary – Winter Wallop for January Market

Latest News

Posted by: Dean Kimoto

The country’s housing market was stone cold in January and the Canadian Real Estate Association is blaming the weather – or at least the weather in parts of southern Ontario. Record setting snowfalls and ferociously cold temperatures appear to have kept house hunters indoors.

Seasonally adjusted sales were down nearly 6.0% in January compared to December. Still, more than 22,500 properties changed hands. The national average sales price slipped 2.6% compared to a year earlier.

CREA is not letting the weather cool its expectations for 2026 though. The Association is forecasting 5.1% sales growth and 2.8% price growth in 2026, driven by pent-up demand and a pent-up desire to sell. That desire to sell may be showing itself. New listings rose more than 7.0%, tipping the market further in favour of buyers.

There is a feeling among some realtors that, while the weather may have been a factor in January, the slump is a hold-over from the end of 2025. They say buyers, especially first-timers, are waiting for greater improvements in affordability through further price reductions and, perhaps, lower interest rates.

The latest inflation numbers suggest there may be some merit in that thinking. Statistics Canada reports headline inflation dipped to 2.3% in January, down from 2.4% in December. Most of the decline came from falling gasoline prices, but shelter inflation continues to slow as well. It dropped below 2.0% for the first time in five years. Hopes for lower interest rates seem more remote though. The Bank of Canada has been clear, it will not be moving rates unless there are very strong reasons to do so.

This article is reposted from First National Finacial’s Marketing Team.

12 Feb

Brokers weigh benefits and trade-offs of Nova Scotia’s 2% down payment pilot

Latest News

Posted by: Dean Kimoto

The province’s new program lets eligible first-time buyers purchase with just two per cent down through select credit unions, but brokers warn the trade-offs could limit flexibility and increase long-term costs.

Nova Scotia’s new pilot program to help first-time homebuyers enter the housing market is drawing national attention, as industry experts assess how the initiative intersects with federal mortgage insurance rules and whether it could work beyond the province.

The program, announced last week, is being offered through participating credit unions and allows eligible buyers to purchase a home with as little as a two per cent down payment. Nova Scotia will assume the part of the risk typically covered by mortgage insurers.

While the initiative is intended to improve access to homeownership, industry observers say the pilot’s wider, long-term impact will depend on borrower risk, lender participation, and federal insurer support.

Clinton Wilkinson
Clinton Wilkinson

“I like the idea of more people getting into the marketplace and having a lower down payment,” Clinton Wilkins, principal broker at the Halifax, N.S.-based Clinton Wilkins Mortgage Team, told Canadian Mortgage Trends. “But the concern for me is if you’re only putting down two per cent, do you have no other resources? What happens if something goes wrong in the home as well? There’s no fallback position.”

Under the pilot, eligible applicants must have a household income below $200,000, a minimum credit score of 630, and meet standard stress-test requirements.

The program applies to owner-occupied homes priced up to $570,000 in Halifax Regional Municipality and East Hants, and $500,000 elsewhere in the province. Loans issued under the pilot are not insured by federal agencies. Instead, the province provides a deficiency guarantee in place of traditional mortgage insurance.

Because the provincial guarantee is tied to participating credit unions and is not transferable, borrowers would generally need to build at least 20% equity before refinancing or moving the mortgage to another lender.

Concerns about flexibility and long-term costs

Some brokers say those conditions could limit borrowers’ flexibility and increase their long-term borrowing costs.

“The cost of borrowing from a credit union in Nova Scotia is typically one to two per cent higher than we would get from another prime lender,” Wilkins says. “If you’re only putting down two per cent and have no high-ratio insurance, you’re going to be stuck with that credit union likely for five, 10, or 15 years.”

Wilkins says the program could be more beneficial in rural parts of the province, where credit unions often play a larger role in mortgage lending and access to traditional bank branches, and brokers are more limited.

He noted that in those markets, the initiative could help expand homeownership opportunities for buyers who may otherwise face fewer financing options. By contrast, he said the program could negatively impact Halifax’s already competitive housing market.


“The average price point in Halifax is over $600,000,” Wilkins said. “I fear that it may put some additional stress on that sub-$570,000 price point.”

Could the model go national?

Others say the program’s broader impact will depend on how well it aligns with federal mortgage insurance rules and provincial housing policy.

Leigh Graham
Leigh Graham

Leigh Graham, a Kingston, Ont.- based broker and partner at The Mortgage Professionals, says the pilot program highlights the complexity of coordinating provincial affordability initiatives with federal lending frameworks. “When somebody’s buying with less than 20% down and they need the government insurance, the insurance factor is still a federal matter,” Graham says.

However, if a government insurer like Canada Mortgage and Housing Corporation decides the program is viable, Graham says there’s no reason it couldn’t or shouldn’t spread across the country. It would just depend on how lenders engage with the program at a provincial level.

Graham notes that down payment requirements are only one part of the affordability equation. “Qualification remains the single largest challenge,” he says. “Starter home prices in many Ontario markets are much higher than what average incomes will allow.”

Implications for consumer choice

Given the Nova Scotia pilot’s limitation to 14 specific credit unions, Graham cautions that the structure could restrict consumer choice. “It could end up being a potentially proprietary program for specific lenders,” he says. “That could be challenging for a consumer.”

Michelle Drover
Michelle Drover

Michelle Drover, vice-president at Halifax-based Premiere Mortgage Centre, says buyers who enter the pilot through credit unions may face significant constraints when their terms expire. “If somebody takes this product with the credit union, they have no equity,” Drover said. “When the mortgage comes up for renewal, where are they going to switch it? They can’t transfer it to an insured lender because it’s not insured.”

She said limited mobility can weaken borrowers’ negotiating power over time. “We’re in this industry because we’re advocates for our clients,” she said. “We want to ensure that they have options available to them.”

Drover added that first-time buyers should carefully compare the pilot with other available programs before committing. “Go with your eyes wide open and look at all of the options available to you,” she said. “[This] looks pretty, but when you unwrap it, it’s not very pretty inside.”

Written by Andrew Seale, Mortgage Industry News, February 12, 2026 and sourced from Canadian Mortage Trends.

5 Feb

Toronto, Vancouver show biggest signs of mortgage stress: CMHC

Latest News

Posted by: Dean Kimoto

The Canada Mortgage and Housing Corp. says it sees signs of financial stress among homeowners in Toronto and Vancouver, with missed mortgage payments projected to steadily increase.

First-time buyers who purchased during the COVID-19 pandemic when interest rates were lower also show greater signs of vulnerability.

Figures from CMHC show that while missed mortgage payments have risen, they are at historic lows. The report says some borrowers are extending their amortization periods to help lower their monthly payments.

The national housing agency says more than 1.5 million households have renewed their mortgage at higher interest rates, with another million expected to do so in the coming year.

Tania Bourassa-Ochoa, CMHC deputy chief economist, says most Canadians have been resilient while facing higher interest rates at renewal.

She says extending the length of a mortgage has helped households manage short-term finances, but it comes at a greater longer-term expense.

Written by

The Canadian Press
Mortgage Industry News, Mortgage Industry News
February 5, 2026

4 Feb

Vancouver home sales continue sluggish pace to kick of 2026: real estate board

Latest News

Posted by: Dean Kimoto

Real estate activity in the Vancouver area got off to a slow start this year as residential sales in the region totalled 1,107 last month, down 28.7% from January 2025.

Greater Vancouver Realtors says the number of properties that changed hands was also 30.9% below the 10-year seasonal average.

The composite benchmark price for all residential properties was $1,101,900, down 5.7% from the same time last year and 1.2% lower than December.

The board’s chief economist and vice-president of data analytics Andrew Lis says that while the January data may “appear alarming,” the quiet pace to kick off 2026 is unsurprising after last year ended with one of the lowest sales totals in more than two decades.

There were 5,157 new listings on the market last month, down 7.3% from a year earlier but 19.4% above the 10-year average.

Total inventory grew 9.9% year-over-year to 12,628, which was 38% above the long-term average.

Written by:

The Canadian Press
Real Estate
February 3, 2026

10 Dec

Bank of Canada maintains policy rate at 2¼%

Latest News

Posted by: Dean Kimoto

The Bank of Canada today held its target for the overnight rate at 2.25%, with the Bank Rate at 2.5% and the deposit rate at 2.20%.

Major economies around the world continue to show resilience to US trade protectionism, but uncertainty is still high. In the United States, economic growth is being supported by strong consumption and a surge in AI investment. The US government shutdown caused volatility in quarterly growth and delayed the release of some key economic data. Tariffs are causing some upward pressure on US inflation. In the euro area, economic growth has been stronger than expected, with the services sector showing particular resilience. In China, soft domestic demand, including more weakness in the housing market, is weighing on growth. Global financial conditions, oil prices, and the Canadian dollar are all roughly unchanged since the Bank’s October Monetary Policy Report (MPR).

Canada’s economy grew by a surprisingly strong 2.6% in the third quarter, even as final domestic demand was flat. The increase in GDP largely reflected volatility in trade. The Bank expects final domestic demand will grow in the fourth quarter, but with an anticipated decline in net exports, GDP will likely be weak. Growth is forecast to pick up in 2026, although uncertainty remains high and large swings in trade may continue to cause quarterly volatility.

Canada’s labour market is showing some signs of improvement. Employment has shown solid gains in the past three months and the unemployment rate declined to 6.5% in November. Nevertheless, job markets in trade-sensitive sectors remain weak and economy-wide hiring intentions continue to be subdued.

CPI inflation slowed to 2.2% in October, as gasoline prices fell and food prices rose more slowly. CPI inflation has been close to the 2% target for more than a year, while measures of core inflation remain in the range of 2½% to 3%. The Bank assesses that underlying inflation is still around 2½%. In the near term, CPI inflation is likely to be higher due to the effects of last year’s GST/HST holiday on the prices of some goods and services. Looking through this choppiness, the Bank expects ongoing economic slack to roughly offset cost pressures associated with the reconfiguration of trade, keeping CPI inflation close to the 2% target.

If inflation and economic activity evolve broadly in line with the October projection, Governing Council sees the current policy rate at about the right level to keep inflation close to 2% while helping the economy through this period of structural adjustment. Uncertainty remains elevated. If the outlook changes, we are prepared to respond. The Bank is focused on ensuring that Canadians continue to have confidence in price stability through this period of global upheaval.

Information note
The next scheduled date for announcing the overnight rate target is January 28, 2026. The Bank’s next MPR will be released at the same time.

This article was posted on the Bank of Canada Website

16 Oct

BMO CEO White urges Canada to cut taxes even if deficit widens

Latest News

Posted by: Dean Kimoto

Canada is “absolutely not” competitive on tax policy, said Bank of Montreal Chief Executive Officer Darryl White, who called on the federal government to cut taxes even if it means running a larger deficit.

Darryl White, chief executive officer of BMO Financial Group, speaks during the US-Canada Summit in Toronto, Ontario, Canada, on Tuesday, April 4, 2023. The event will focus on politics, trade, tech innovation, security, energy, and the environment.

By Christine Dobby

(Bloomberg) — Canada is “absolutely not” competitive on tax policy, said Bank of Montreal Chief Executive Officer Darryl White, who called on the federal government to cut taxes even if it means running a larger deficit.

With trade issues dominating the national debate, tax incentives for investment aren’t getting enough attention, White said Wednesday at the Toronto Global Forum.

Prime Minister Mark Carney’s government cancelled an unpopular increase to the capital-gains inclusion rate, but it needs to go further, White said, such as by letting businesses write off capital assets sooner and lowering corporate and personal taxes.

“We have a little bit of fiscal capacity to play with here,” he said. While he’s normally a supporter of balanced budgets, “this is a moment where — throw that out the window and take a little bit more risk.”

He said Canada should seize the momentum created by U.S. President Donald Trump’s trade policies, which have prompted a rethink of internal barriers to trade and Canadian exporters’ dependence on the U.S. market.

“Are we letting a crisis go to waste? Are we competitive on tax? I know the answer to that is, ‘Absolutely not,’” he said.

In July, the federal government cut the country’s lowest income tax rate by one percentage point.

White, who’s led the country’s third-largest bank by market capitalization for almost eight years, said capital will “flow to the point of least resistance” — and Canada must make itself a destination. Other top executives, including other bank CEOs, have also pressed Ottawa for tax reform.

Carney’s government is set to unveil its first budget on Nov. 4, with the federal deficit expected to climb to at least $70 billion. National Bank of Canada Chief Economist Stefane Marion predicts a shortfall of about $100 billion, saying Ottawa will likely deliver a “stimulative budget.”

“We do have some fiscal room when you compare Canada to the rest to the world,” Marion said at a Bloomberg event last week. “We should not waste it.”

©2025 Bloomberg L.P.

24 Sep

‘Wake up’: Bank CEO urges Carney to fight U.S. with radical tax cuts

Latest News

Posted by: Dean Kimoto

National Bank of Canada’s top executive called on Prime Minister Mark Carney to consider bold tax cuts and deregulation for strategic sectors to boost the country’s productivity and competitiveness.

By Mathieu Dion

(Bloomberg) — National Bank of Canada’s top executive called on Prime Minister Mark Carney to consider bold tax cuts and deregulation for strategic sectors to boost the country’s productivity and competitiveness.

“We need to have lower taxes than the U.S. for businesses,” Chief Executive Officer Laurent Ferreira said at the Canada Fintech Forum in Montreal on Monday evening. The government should even think about a “zero tax policy” for strategic manufacturing and defense procurement, he said.

Ferreira, who has led Canada’s sixth-largest bank since 2021, told the audience the country’s productivity growth has been weak for a decade. “We need to wake up,” he said, also calling for fewer regulatory requirements in the manufacturing sector.

“We need to be more competitive. We have a hard time attracting capital. We have a hard time keeping our businesses in Canada.”

U.S. President Donald Trump’s tariff policies have sent a chill through Canada’s economy over the past several months. Gross domestic product contracted at a 1.6% annualized pace in the second quarter amid a drop in exports and soft business investment.

Most Canadian goods are still exempt from new U.S. levies under the U.S.-Mexico-Canada Agreement. But Trump’s tariff policy has shaken the automotive, steel and aluminum industries, and the unpredictable outcome of a new deal is leading many companies to wait before investing.

“No one really knows how tariffs are going to impact the U.S., Canada, and growing deficits around the world are also a big question mark for the bond market,” Ferreira said. “Those are obviously uncertainties that are around that and clients, businesses are on pause.”

Carney has promised to release a federal budget on Nov. 4 with substantial investments to boost the country’s economy. The government trimmed personal income taxes in July, but hasn’t indicated it’s considering large cuts to business taxes.

Canada faces significant budget pressures, partly because of increased military spending. The deficit will be about $70 billion this fiscal year, or more than 2% of GDP, according to the median estimate in a Bloomberg survey of economists.

Still, Ferreira praised the federal and provincial governments’ focus since the beginning of the trade war. “It’s an economic agenda, and it is very encouraging to hear everything that they’re working on,” he said about his discussions with government officials.

©2025 Bloomberg L.P.

17 Jul

Fixed mortgage rates creep higher as bond yields rise

Interest Rates

Posted by: Dean Kimoto

Lenders have started raising fixed mortgage rates again, with signs pointing to a short-term upward trend.

Fixed mortgage rates have been creeping upward over the past week, fuelled by a modest rebound in bond yields following stronger-than-expected economic data.

The increases were partly driven by rising U.S. Treasury yields, with the 5-year rising above 4% following stronger-than-expected inflation data. That, in turn, helped lift Canadian bond yields, which are closely linked to their U.S. counterparts.

On this side of the border, Canada’s strong June employment report added to the momentum. Since fixed mortgage rates are closely tied to government bond yields, the upward pressure was enough to prompt some lenders to raise pricing, particularly on 3- and 5-year terms.

Rate hikes of around five to 10 basis points (0.05 to 0.10 percentage points) were seen by some lenders over the past week, with further increases continuing into this week.

While the changes varied by lender, they reflect what some observers see as a short-term trend toward higher fixed rates.

“Some lenders responded by increasing their fixed mortgage rates on Friday and I expect others to follow,” wrote mortgage broker Dave Larock. “Those increases are consistent with my recent assessment that bond yields, and the fixed mortgage rates that are priced on them, now have an upward bias.”

Ron Butler of Butler Mortgage said the upward move in longer-term yields is also being shaped by broader fiscal pressures. “The spectre of growing government deficits all over the world is creating capacity concerns,” he told Canadian Mortgage Trends.

He added that 3- to 5-year fixed mortgage rates—currently in the 4% range—will likely stay around these levels for the next few months.

Inflation data firm expectations for BoC hold

Larock noted that while June’s jobs data may not significantly affect the Bank of Canada’s rate outlook, the June inflation results released Tuesday will. Statistics Canada reported that the country’s annual inflation rate ticked up to 1.9% in June, with core inflation measures remaining stubborn.

That firmed expectations the Bank of Canada will hold its key rate on July 30, which would mean no change for existing variable-rate and HELOC borrowers.

“The central bank will almost certainly hold this month,” Butler said, though he still sees the potential for a cut later in the year. “No cuts from the BoC in July or September seem likely, but I expect one in October or December as the economy worsens.”

Many fixed terms still closely priced

Despite the recent hikes, Larock pointed out that fixed rates remain below their long-term averages. Term premiums, which are typically the extra cost of locking in for longer, are starting to return, but many popular fixed terms are still priced similarly.

In cases where 3- and 5-year terms are comparable, Larock said he continues to favour the 5-year fixed.

He added that variable rates are likely to deliver the lowest overall borrowing cost over time, assuming rate cuts materialize as expected. But he cautions that variable-rate borrowers need to be prepared for continued volatility and higher payments if the timing of those cuts shifts further out.

“Anyone choosing a variable rate should do so only if they can live with its inherent potential for volatility and if they have the financial capacity to withstand higher costs (and, in some cases, higher payments) should my forecast prove incorrect,” he wrote.

This article was written for Canadian Mortgage Trends by:

Steve Huebl

Steve Huebl is a graduate of Ryerson University’s School of Journalism and has been with Canadian Mortgage Trends and reporting on the mortgage industry since 2009. His past work experience includes The Toronto Star, The Calgary Herald, the Sarnia Observer and Canadian Economic Press. Born and raised in Toronto, he now calls Montreal home.

9 Jul

Mortgage Digest: RBC expects no further BoC rate cuts

Latest News

Posted by: Dean Kimoto

Canada’s big banks are divided on how much further the Bank of Canada will cut, with RBC now saying the rate has likely bottomed, while others still expect more easing ahead.
Fed’s interest rate hike policy. Profits from raising interest rates or investments. A businessman looking through a telescope standing next to a percentage sign. flat vector illustration.

The outlook for interest rates is becoming less clear-cut as Canada’s major banks rethink how far the Bank of Canada will go in its rate-cutting cycle. While most still see room for further easing, RBC is breaking away from the pack.

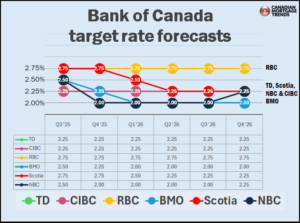
The bank has taken additional cuts off the table, forecasting the overnight rate will hold steady at 2.75% through 2026—making it the most hawkish forecast among the Big Six.

In its latest Monthly Forecast Update, RBC said: “We no longer expect any rate cuts from the BoC this year.” The bank explained that “as direct trade uncertainty facing Canada recedes…the inflation outlook remains uncertain,” reducing pressure on the central bank to act further.

That’s a shift from earlier this year, when RBC still expected one more cut before the cycle ended.

By contrast, Scotiabank has revised its forecast lower, now projecting the policy rate to settle at 2.25%—down from 2.50% in its previous estimate. BMO, meanwhile, remains the most dovish, continuing to project a fall to 2.00% by early 2026.

TD, CIBC and National Bank continue to expect a terminal rate of 2.25%, in line with the Bank of Canada’s current inflation outlook.
CMBS delinquencies edge down as payoff activity stays strong

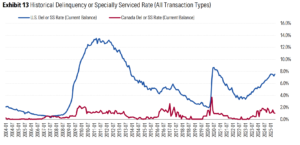
Canadian CMBS delinquencies ticked lower in May, with Morningstar DBRS reporting a 1.0% delinquent or specially serviced rate—down from 1.1% in April and well below the U.S. rate of 7.5%.

According to Morningstar DBRS, overall maturity payoff rates held at 100%, with no realized losses reported in May. Loans across all size categories and debt service coverage ratio (DSCR) tiers were paid in full at maturity or prepaid ahead of schedule.

The number of loans still operating under pandemic-era forbearance also continued to decline. As of May, 19 loans with deferred balances remain, though most have resumed regular payments. Outstanding balances tied to forbearance are now concentrated in select property types—particularly retail and hotel assets—and are mostly located in Ontario and Quebec.

Morningstar DBRS also flagged that while most COVID-impacted loans are performing again, a few continue to show signs of strain, particularly those in regions hit hard by broader economic shifts.

Overall, the report suggests continued resilience in the Canadian CMBS market, with improving delinquency trends and strong repayment performance.
Ontario credit union assets edge higher in Q4, but mortgage growth remains slow

Ontario’s credit unions continued to expand their balance sheets in Q4 2024, with total assets rising to $99.61 billion, up 3.37% year-over-year, according to FSRA’s latest Sector Outlook report.

Growth was led by a $1.42-billion jump in commercial lending and a 9.44% increase in cash and investments. Residential mortgage growth remained muted, up just 1.02% annually, reflecting subdued housing activity.

Profitability improved slightly, with return on average assets rising to 0.24%, up three basis points from Q3, driven by lower interest paid to depositors.

However, credit quality showed some deterioration. The delinquency rate on residential mortgages climbed to 0.87%, up 31 basis points from a year earlier.

FSRA noted the broader debt picture is improving, as StatCan data shows Canada’s household debt-to-income ratio declined to 170.1% in Q3 2024, down from 175.0% a year earlier.


Many renters still holding off on buying, despite falling rates and prices

More than a quarter of Canadian renters considered buying before signing or renewing their current lease, according to a new Royal LePage survey, but most ultimately chose to wait.

Even with home prices softening and borrowing costs easing, 40% of surveyed renters said they’re holding out for even lower prices. Another 29% are waiting for further rate cuts, while 28% say they’re still saving for a down payment.

Despite these hurdles, 54% of renters say they plan to buy eventually. Of those, 16% hope to do so within two years, and 21% within five.

“Entry-level opportunities have improved significantly,” said Royal LePage CEO Phil Soper, who noted that incomes are rising and some of the least affordable cities are becoming more accessible. “Still, many renters… are choosing to wait. History suggests they may be disappointed.”

A growing supply of purpose-built rentals and softer demand—partly due to capped international student permits—has also eased rental prices. According to Rentals.ca and Urbanation, average national rents for one- and two-bedroom units declined 3.6% and 4.6% year-over-year, respectively, in May.

Still, affordability remains an issue. Nationally, 37% of renters spend between 31% and 50% of their net income on rent, and 15% spend more than half. Many are also cutting back—on groceries, savings, or even taking on second jobs—to keep up.

“Even with several months of decreases, rents are still significantly higher than they were just a few years ago,” Soper said, calling for “meaningful policy action” to restore long-term affordability.


Mortgage arrears edged up slightly in April

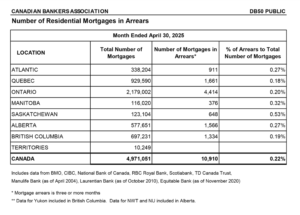
The number of Canadian mortgages in arrears ticked up slightly in April, reaching 10,910 loans, or 0.22% of all residential mortgages, according to the latest data from the Canadian Bankers Association.

Saskatchewan continues to report the highest arrears rate in the country at 0.53%, followed by Manitoba at 0.32% and both Atlantic Canada and Alberta at 0.27%. In contrast, Quebec (0.18%), British Columbia (0.19%), and Ontario (0.20%) all remain below or near the national average.

Despite the modest increase, arrears levels remain low by historical standards, and well below the current 1.52% mortgage arrears rate in the U.S.
This is most of an article written for Canadian Mortgage Trends (click for full article) by:

Steve Huebl

Steve Huebl is a graduate of Ryerson University’s School of Journalism and has been with Canadian Mortgage Trends and reporting on the mortgage industry since 2009. His past work experience includes The Toronto Star, The Calgary Herald, the Sarnia Observer and Canadian Economic Press. Born and raised in Toronto, he now calls Montreal home.
10 Jun

GST relief on new homes could save 1st-time buyers up to $240 on mortgages: report

Latest News

Posted by: Dean Kimoto

The Liberal plan to give first-time homebuyers a tax break on a newly built home could have substantial impacts on housing affordability — with a few caveats — a new analysis finds.

The Liberal government introduced legislation on June 5 to eliminate the GST portion from new home sales of up to $1 million for first-time buyers, which works out to as much as $50,000 off the cost of a new build or a substantially renovated unit.

For homes sold above $1 million, the GST relief is phased out as the price tag nears $1.5 million.

Desjardins Economics said in a report released Monday that first-time Canadian homebuyers could save up to $240 on their monthly mortgage payments if they were to buy a new home with an all-in, tax-included price of $1 million. The required down payment would also be somewhat smaller.

Some developers charge the sales tax upfront, so it’s not rolled into the mortgage principal at the time of purchase.

“For these homes, eliminating the GST will help prospective buyers reduce upfront closing costs, helping them get their foot in the door sooner,” said the report, authored by Desjardins economist Kari Norman.

She argued the impact on housing affordability will be “particularly strong” for buyers in Canada’s more expensive markets, like Toronto and Vancouver, where homes are routinely priced above the $1-million mark.

The new policy takes a big step beyond the existing New Housing Rebate, which is open to more than just first-time buyers but has long been capped at homes priced up to $450,000.

Norman estimates that nearly 85% of new builds in Canada would quality for up to $50,000 GST relief in the new proposal.

Roughly 92% of new builds in Toronto are expected to qualify for full or partial tax relief for homes priced up to $1.5 million. Only 75% of new units in Vancouver would qualify, however, as many top out of the qualifying price range.

Desjardins recommends that the new policy index the price of qualifying homes to inflation to avoid future erosions in affordability.

The federal government predicts the GST rebate will cost about $3.9 billion over five years, while the parliamentary budget officer estimates the price tag is closer to $2 billion over the same time frame.

Desjardins said the discrepancy between the figures could indicate the federal government anticipates more new buyers taking advantage of the rebate, and a bigger boom in homebuying and construction as a result.

It’s possible that increased demand spurred by the policy also leads to a surge in new building in Canada, the report said.

The rebate also comes at a time when the Canadian construction industry faces serious obstacles to getting shovels in the ground: high financing and construction costs, regulatory delays, an aging workforce and uncertainty among buyers and builders tied to Canada’s trade war with the United States.

The report also warns that some developers, foreseeing increased buying power, could raise their own costs for materials and labour in response to the policy, which would undermine any gains in affordability.

Higher demand for housing tied to the GST break could, in the near-term, push up home prices if not coupled with other efforts to boost supply and the pace of construction, the report said.

This might be the ideal time to introduce a policy that stokes demand for new builds, however, as Desjardins noted a particularly soft condo market in cities such as Toronto could benefit from an increase in buyer appetite.

Parliament has yet to pass the legislation, which would apply to homes bought between May 27 through to 2031. Construction on qualifying homes would need to start before 2031 and finish by 2036.

The measure, one of a suite of proposals included in the Liberal platform during the spring federal election, is packaged in the same legislation as the promised income tax cut, which is set to take effect July 1.

This article was written for Canadian Mortgage Trends by Craig Lord.