7 Sep

Vancouver-area home sales down nearly 5% in August amid second-half lag

Latest News

Posted by: Dean Kimoto

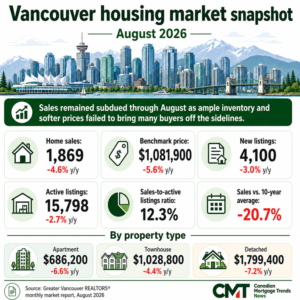
Home sales in the Vancouver region dropped 4.6% last month compared with a year ago, continuing a lag since May that is expected to persist through the end of 2026.

Greater Vancouver Realtors says there were 1,869 home sales last month, which was 20.7% below the 10-year seasonal average.

Andrew Lis, the board’s chief economist and vice-president of data analytics, says inventory levels have receded from their 2025 heights, and paired with slower-than-usual sales, this has caused prices “to drift downwards across all market segments.”

The composite benchmark price for all types of residential properties in Vancouver was $1,081,900, a 5.6% decline from August 2025 and a 0.6% dip from July 2026.

There were 4,100 new listings on the market last month, down three per cent year-over-year and 1.3% lower than the 10-year average.

Meanwhile, total inventory fell 2.7% annually to 15,798, which was 26.2% above the long-term average.

This article is re-posted from the Canadian Mortgage Trends website.

4 Sep

Canada can ride out global bond rout, finance minister says

Latest News

Posted by: Dean Kimoto

Finance Minister Francois-Philippe Champagne said positive investor sentiment is helping keep Canada’s borrowing costs in check despite a global bond rout, arguing the country’s finances are strong enough to handle the volatility.

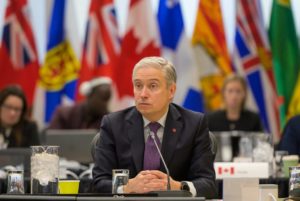
Canadian Finance Minister Francois-Philippe Champagne

By Erik Hertzberg

(Bloomberg) — Finance Minister Francois-Philippe Champagne said positive investor sentiment is helping keep Canada’s borrowing costs in check despite a global bond rout, arguing the country’s finances are strong enough to handle the volatility.

A selloff in government debt has sent the yield on 30-year US Treasuries surging to about 5.27%, creating major headaches for Treasury Secretary Scott Bessent. The Canada long bond is trading much richer, posting a yield of 4.15% as of 3:30 p.m. New York time on Tuesday.

That’s a wider gap than usual. Over the past decade, the Canadian 30-year yield has been about 70 basis points below Treasuries, on average, according to data compiled by Bloomberg.

“The bond market is showing a lot of confidence in Canada, both in the short term and in the long term because of the measures that we’ve been taking,” he told reporters while attending the Group of 20 meetings in Asheville, North Carolina.

Statistics Canada reported record flows of $80.8 billion by foreign investors into government bonds in Canada in the second quarter.

“We‘re entering this period in a position of strength,” Champagne said, “We’ve reduced our expenses, we have increased revenues, but we have also made strategic choices.”

But he added that Canada is “not immune to the geopolitical conflicts that are happening,” citing the ongoing wars in Iran and Ukraine that have disrupted global energy supplies and raised consumer costs.

Relations between the U.S. and Canada appear to be at their worst state in years. After trade talks collapsed on Aug. 21, both sides rolled out new tariffs on each other’s goods. President Donald Trump and other U.S. officials have publicly denigrated Canada.

On Monday, Bessent scoffed at the idea the U.S. was in a trade war with its northern neighbor, asking if Canada was going to “take their two submarines from the Edmonton mall and sic them on us.” That’s a reference to a visitor attraction that was removed from the West Edmonton Mall in 2005.

On Tuesday, Prime Minister Mark Carney said the talks can’t resume until the US stops “throwing shade” at Canada and gets serious about the issues at stake.

Champagne said he plans to be “constructive” yet “firm” as he meets with Bessent on Tuesday.

The benchmark 10-year Canada yield was up about 1 basis point in afternoon trading to 3.745%. That’s the third lowest in the Group of Seven — German and Japanese debt is currently more expensive at that tenor.

But it’s still around 37 basis points higher than at the start of July. The spread with U.S. 10-year notes has narrowed slightly over that period.

Champagne is expected to reveal the new federal budget in the next few months. The government is running deeper deficits, partly to fund infrastructure and housing, and is aiming to draw billions of dollars of investment into Canada.

In April, the finance department projected a $65.3 billion shortfall this fiscal year, representing about 2% of gross domestic product. However, more than half of economists in a Bloomberg survey expect the deficit outlook to be deeper than that.

©2026 Bloomberg L.P.

This article was re-posted from Canadian Mortgage Trends.

19 Aug

Trump delays Canadian tariffs at 11th hour, saying deal close

Latest News

Posted by: Dean Kimoto

The Trump administration delayed 50% tariffs on billions of dollars of Canadian products for three days, saying the two sides had reached a tentative agreement to resolve a broader trade dispute that had plunged relations to a fresh low.
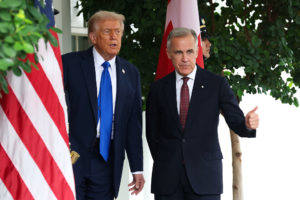
US President Donald Trump and Canadian Prime Minister Mark Carney at the White House on Oct. 7.

By Alicia Diaz and Josh Wingrove

(Bloomberg) — The Trump administration delayed 50% tariffs on billions of dollars of Canadian products for three days, saying the two sides had reached a tentative agreement to resolve a broader trade dispute that had plunged relations to a fresh low.

President Donald Trump announced the decision less than two hours before the tariffs were set to take effect. He said on social media he was pausing the tariffs “based on the fact that Canada and the U.S.A., subject to the finalization of documents, have a DEAL!”

A White House proclamation later said the duties were halted after Canada “expressed a commitment to remove the discriminations” on U.S. autos, dairy and alcohol. And the U.S. Trade Representative’s office said the deal includes “comprehensive market access for all American goods, economic security commitments, digital trade alignment” and other factors, without giving specifics.

Canadian Prime Minister Mark Carney wasn’t as definitive, stopping short of saying they had a deal. Neither side said whether earlier sticking points such as auto tariffs and lumber will be resolved.

“Substantial progress has been made, although there is important work still to be done,” Carney said in a statement. “While we continue this work, Canada remains focused on building a stronger, more independent, and more competitive economy at home.”

The Canadian dollar was up 0.2% at 1.3876 per U.S. dollar mid-morning in London.

Despite the uncertainty, the announcement signals progress in the tense relationship between two longstanding allies that conducted almost $900 billion of trade with each other last year. It also indicates the potential for a step forward in the ongoing review of the North American trade agreement, which also includes Mexico.

Trump had announced the tariffs in late July, justifying them by pointing to Canada’s retaliation against a barrage of tariffs last year, and it wasn’t immediately clear what concessions he’d won from the latest gambit. He has routinely backed off some of his biggest tariff threats when negotiations yield what are often modest concessions.

The White House had said it would put duties on a range of items from Canada — including hockey equipment, beer, milk and plywood — under Section 338 of the 1930 Tariff Act, which gives the president the power to impose duties of as much as 50% on countries deemed to discriminate against U.S. commerce.

Most Canadian provinces, including Ontario and Quebec, have barred U.S. alcoholic beverages from retail stores, cutting off an important export market for American makers of wine and spirits.

Chris Swonger, head of the Distilled Spirits Council of the United States, said exports of U.S. spirits to Canada have dropped 70% in provincial boycotts since 2025.

Spirits boycott
“As discussions continue over the next few days, we encourage leaders on both sides of the border to reach a negotiated solution that gets American spirits back on retail shelves in all Canadian provinces and returns the spirits sector to a zero-for-zero tariff framework,” Swonger said in a statement late Tuesday.

Canada also responded to Trump’s tariffs against autos by placing similar counter-tariffs against U.S.-made cars and trucks — though it created a mechanism for refunding them to companies including Honda Motor Co. that also manufacture vehicles in Canada.

The tariffs were set to go into effect on Wednesday, creating a 30-day window for talks designed to pressure Canada into making concessions. Janice Charette, Canada’s chief trade negotiator, and cabinet minister Dominic LeBlanc stayed in the U.S. capital over the weekend to try to hammer out a deal.

The proposed Section 338 tariffs wouldn’t have applied to the most important resources that the U.S. buys from Canada, such as oil, potash and minerals.

Carney previously said Canada’s goal in trade talks was to reduce the sectoral duties on industries like steel, aluminum and autos, which have created huge uncertainty for the country’s manufacturing base and caused a number of layoffs.

In his Truth Social post announcing the tariff delay, Trump also said the Keystone XL Pipeline would be revived.

Trump has already signed a presidential permit authorizing the Bridger Pipeline expansion project meant to carry Canadian oil to Wyoming — a project that’s a partial revival of the Keystone XL Pipeline, which Trump wanted during his first term. Former President Joe Biden effectively sank that project by withdrawing authorization for it in 2021.

The U.S. imports more than 4 million barrels a day of crude oil and petroleum products from Canada, an amount that has steadily grown for decades. Energy is the US’s largest import from Canada.

Deborah Elms, head of trade policy at the Hinrich Foundation, said in a LinkedIn post on Wednesday that while the deadline extension raises uncertainty for companies trying to trade between the countries, “tariffs on most Canadian goods are still zero, have been at zero for qualifying goods for decades, and may stay at zero.”

–With assistance from Derek Wallbank and Georgia Hall.

©2026 Bloomberg L.P.

This article was resposted from Canadian Mortgage Trends.
14 Jul

Bank of Canada expected to hold as debate shifts to timing of rate hikes

Latest News

Posted by: Dean Kimoto

The Bank of Canada is widely expected to hold its policy rate at 2.25% this week, but economists remain divided over how soon the central bank may need to begin raising rates.

The Bank of Canada is expected to keep its policy rate unchanged at 2.25% on Wednesday, which would mark a sixth consecutive hold.

With a hold now largely priced in, the more consequential question is whether the Bank’s updated forecasts and accompanying language begin to lay the groundwork for rate hikes later this year.

That debate has sharpened as the economy shows signs of recovering from a weak start to 2026, even as inflation remains uncomfortably high. Headline inflation has climbed above 3%, driven largely by higher energy costs, while recent GDP and employment data suggest the economy may be emerging from its early-year soft patch.

BMO senior economist Benjamin Reitzes said the bar for a move in either direction remains high. The recent improvement in economic data gives the Bank little reason to cut, while continued slack in the economy should keep policymakers from rushing to raise rates.

“The economic data have turned up recently following a miserable run,” Reitzes wrote. However, he said the economy’s persistent output gap should continue to generate disinflationary pressure and limit the Bank’s willingness to tighten policy.

He said lower oil prices should ease some of the Bank’s immediate concerns, but policymakers will continue watching for signs that higher energy and transportation costs are spreading more broadly. With the 2021-to-2023 inflation surge still fresh, the key issue is whether the rise in headline inflation proves temporary or begins to influence wages, inflation expectations and the wider consumer price basket.

Updated forecasts could reveal a more hawkish tilt

The Monetary Policy Report, which sets out the Bank’s updated forecasts for growth and inflation, may offer a clearer signal than the rate announcement itself.

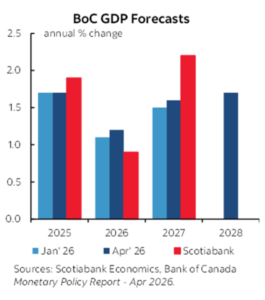
Scotiabank economist Derek Holt expects the Bank to mark down its first-quarter outlook after GDP contracted slightly rather than expanding as forecast. That weakness may be offset by a stronger rebound in the second quarter, which Holt estimates may have exceeded 2%, above the Bank’s April projection of 1.5%.

“The BoC may need to revise down its 2026 GDP growth forecast in marked-to-market fashion after Q1 GDP disappointed,” Holt wrote, adding that a stronger second quarter could provide a partial offset.

Scotiabank says inflation remains the tougher part of the outlook, with headline CPI reaching 3.2% in May—above the Bank’s projected 3% peak—and a weaker Canadian dollar, elevated input costs and firmer short-term core measures still pointing to upside risk despite lower oil prices.

Holt said the Bank may need to revise its 2026 inflation forecast upward, arguing that Canada appears to be moving out of its winter “inflation soft patch.”

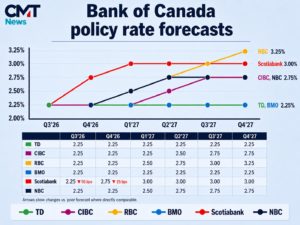
Scotiabank sees those pressures eventually pushing the Bank to withdraw some stimulus, with two quarter-point hikes expected before year-end and a third in early 2027. That would take the policy rate to 2.75% by December and 3% shortly thereafter.

Big banks differ mainly on when hikes begin

The latest forecasts show a growing divide over how long the Bank can remain on hold—and how quickly rates may rise once tightening begins.

TD and BMO expect the policy rate to stay at 2.25% through the end of 2027. CIBC and National Bank see hikes beginning next year, while RBC projects a more gradual tightening cycle that takes the rate to 3.25% by the end of 2027.

Scotiabank remains the most aggressive forecaster, with hikes beginning in the fourth quarter of this year and the policy rate reaching 3% in early 2027.

This article was written for Canadian Mortgage Trends by:

Steve Huebl

Steve Huebl is a graduate of Ryerson University’s School of Journalism and has been with Canadian Mortgage Trends and reporting on the mortgage industry since 2009. His past work experience includes The Toronto Star, The Calgary Herald, the Sarnia Observer and Canadian Economic Press. Born and raised in Toronto, he now calls Montreal home.

18 Mar

Bank of Canada maintains policy rate at 2¼%

Latest News

Posted by: Dean Kimoto

The Bank of Canada today held its target for the overnight rate at 2.25%, with the Bank Rate at 2.5% and the deposit rate at 2.20%.

The war in the Middle East has increased volatility in global energy prices and financial markets, and heightened the risks to the global economy. The breadth and duration of the conflict, and hence its economic impacts, are highly uncertain.

Prior to the war, the global economy was on pace to grow at around 3%, as expected in the January Monetary Policy Report (MPR). Economic growth in the United States has moderated but remains solid, driven by consumption and strong AI-related investment. US inflation remains above target and has evolved largely as expected. In the euro area, domestic demand is supporting growth while exports have contracted. China’s economy continues to be boosted by strength in exports, but domestic demand remains weak.

Since the outbreak of the conflict in the Middle East, global oil and natural gas prices have risen sharply, and this will boost global inflation in the near-term. In addition to energy supply disruptions, transportation bottlenecks stemming from the effective closure of the Strait of Hormuz could impact the supply of other commodities, such as fertilizer. Financial conditions have tightened from accommodative levels. Global bond yields have risen, equity market prices have declined, and credit spreads have widened. The Canada-US dollar exchange rate has remained relatively stable.

After expanding by 2.4% in the third quarter of last year, GDP in Canada contracted 0.6% in the fourth quarter. This was weaker than expected at the time of the January MPR, but mainly because of a larger-than-expected drawdown in inventories. Domestic demand grew by more than 2% due to strength in consumer and government spending, even as housing markets remained weak.

We continue to expect the Canadian economy to grow modestly as it adjusts to US tariffs and trade policy uncertainty, but recent data suggest that near-term economic growth will be weaker than anticipated in January. The labour market remains soft. Employment gains in the fourth quarter of 2025 were largely reversed in the first two months of 2026, and the unemployment rate rose to 6.7% in February. Looking through the volatility, recent data also suggest ongoing weakness in exports. It’s too early to assess the impact of the conflict in the Middle East on growth in Canada.

CPI inflation eased further to 1.8% in February, down from 2.3% in January. CPI inflation excluding changes in indirect taxes as well as core inflation measures have also come down and are all close to 2%. Food inflation slowed in February but remains elevated. The sharp increase in global energy prices has led to increases in gasoline prices, and this will push up total inflation in the coming months.

Against this overall backdrop, Governing Council decided to maintain the policy rate at 2.25%. With recent data pointing to weaker economic activity and uncertainty elevated, risks to growth look tilted to the downside. At the same time, inflation risks have gone up due to higher energy prices. We will continue to assess the impact of US tariffs and trade policy uncertainty, and how the Canadian economy is adjusting. We are also monitoring the unfolding conflict in the Middle East closely and assessing its impact on growth and inflation. As the outlook evolves, we stand ready to respond as needed. The Bank is committed to ensuring that Canadians continue to have confidence in price stability through this period of global upheaval.

Information note

The next scheduled date for announcing the overnight rate target is April 29, 2026. The Bank’s next MPR will be released at the same time.

This article is reposted from the Bank of Canada website.

17 Mar

Canadian inflation decelerates to 1.8% on base effect

Latest News

Posted by: Dean Kimoto

Canada’s inflation rate slowed by more than expected last month after a sales tax break rolled out of yearly comparisons.

                 A shopper walks through St. Lawrence Market in Toronto.

By Nojoud Al Mallees

(Bloomberg) — Canada’s inflation rate slowed by more than expected last month after a sales tax break rolled out of yearly comparisons.

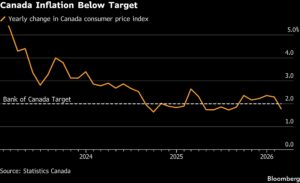
Headline inflation fell to 1.8% in February from 2.3% in January, Statistics Canada reported on Monday. That’s lower than the 1.9% expected by economists surveyed by Bloomberg.

A temporary sales tax break introduced by former prime minister Justin Trudeau on a range of goods, including restaurant meals and children’s toys, expired in the middle of February last year.

While the tax holiday initially drove yearly headline inflation higher because of base effects, it’s now reversing and causing a deceleration that will likely affect March inflation data as well.

Core measures of inflation also eased by more than expected in February. The consumer price index excluding food and energy was up 2%, while the central bank’s median and trim measures of inflation both fell to 2.3%.

Canada bonds rallied across the curve, with the two-year yield down 6.3 basis points to 2.725% as of 9:14 a.m. in Ottawa.

Shelter prices continued to decelerate last month, and were up just 1.5% from a year ago, the slowest pace in five years amid weak housing resales and smaller rent price increases.

Prices for food — which has been a major sore spot for Canadian consumers — also rose at a slower rate. Yearly inflation on food purchased from stores was 4.1% in February from 4.8% the previous month. The deceleration was led by weaker price growth for frozen or fresh beef.

Still, grocery prices are up a cumulative 30.1% over the past five years.

Meanwhile, a more modest year-over-year deceleration in gasoline prices last month moderated the slowdown in headline inflation, with prices at the pump down 14.2% compared to 16.7% in January.

Gasoline prices were up 3.6% on a monthly basis, largely driven by an increase in oil prices ahead of the Middle East conflict and oil supply disruptions in some producer countries, Statcan said.

Andrew DiCapua, an economist at the Canadian Chamber of Commerce, said higher oil prices from the conflict in Iran are likely to show up in next month’s data too.

“For the Bank of Canada, the signals remain mixed with jobs data and inflation pulling them in different directions. That uncertainty for now will likely keep the Bank on hold at this week’s meeting as it waits for a clearer picture,” DiCapua said in an email.

On Friday, Statistics Canada reported the country lost 83,900 jobs in February, the biggest decline in more than four years.

Policymakers are widely expected to keep the benchmark interest rate unchanged at 2.25% on Wednesday.

–With assistance from Mario Baker Ramirez.

©2026 Bloomberg L.P.

This article was reposted from the Canadian Mortgage Trends website.

5 Mar

Slower housing market mixed blessing for those looking to move up property ladder

Latest News

Posted by: Dean Kimoto

A cooling housing market has been good news for those looking to buy their first home, but for homeowners looking to move up the property ladder, the slowdown is more of a mixed blessing.

By Craig Wong, re posted from the Canadian Mortgage Trends website

If you need to sell a home and buy another, the easing in the market adds complexity to your decision.

Davelle Morrison, a broker at Bosley Real Estate Ltd. Brokerage, says it depends on your local market when deciding whether to sell your home first or find your next home and then put your current place up for sale.

“It is important to recognize what kind of market that you’re in, in terms of whether you buy first or sell first,” she said.

“Right now, we’re in that kind of a market where it really does make sense to sell first.”

If you’re looking for a house to buy, a slower market means there will be less of a chance that you’ll find yourself in a bidding war for your new home. That’s good news for potential homebuyers who faced a red-hot market just a few years ago.

But most homeowners need the proceeds from the sale of their current home to make the down payment on the new one and the easing in the market also means it might be harder or take longer than expected to sell your existing property.

That means if you have an offer accepted on a new place without a deal to sell your current home, you’ll have to find a way to bridge the transition financially or delay the closing of the deal until you sell if you don’t want to lose out on the new place.

But if you sell first and close on the sale before you find a home you love to move to, you could find yourself scrambling to find somewhere to lay your head until you find somewhere new to call home.

Morrison said it is important to honest with yourself when it comes to the process of finding a new place.

“If you’re the kind of person who’s extremely, extremely picky and you’re looking for something that’s really specific that doesn’t come out on the market very often, you might need to consider buying first because you might not find what you need if you sell first,” she said.

If that’s the case, Morrison said it is important to take steps to protect yourself.

If you find your dream home before you have a signed deal on your own home and still want to make an offer, she says you’ll want to consider making your offer conditional on the sale of your home.

Anne Alkok, the broker of record at Wahi Realty Inc., said in a hot market a seller might be unwilling to accept such a restriction, but a Realtor can help you understand the current market in your area.

“You do have to be familiar with the market conditions,” she said.

Bridge financing might also be an option, but you’ll have to check with your lender to see if you qualify in addition to qualifying for your mortgage.

A short-term loan to buy your new home before the old one sells could be an option, but it will add costs as interest rates are typically higher than in conventional lending.

Alkok said if your budget is tight and your next purchase depends heavily on what you net from the sale, selling first will give you a clear idea of how much you’ll be able to afford when making your own offer.

Whereas, she says, if you are in a stronger financial position, then you might have more flexibility. “But carrying properties even temporarily does cost money. So it does have to be planned carefully,” she said.

Alkok said there isn’t one choice that works for everyone and it is important to know what you are comfortable with.

“Some people want the certainty. They want to know exactly what their home sells for before they shop. Other people are comfortable making a move first because they’re confident that their home will sell and that they have the financial flexibility to manage the timing.”

27 Feb

Can Canadian investors, advisors manage the mortgage renewal cliff?

Latest News

Posted by: Dean Kimoto

The management of one crisis often creates another. That was the case during the COVID-19 pandemic when central banks cut interests rates to almost zero in the hopes that they could keep a generational health crisis from becoming a spiralling economic crisis. Between late March of 2020 and February of 2022, the Bank of Canada’s key interest rate was 0.25 per cent. The prime lending rate over that same period, according to ICICI Bank, was 2.45 per cent. Those cuts sparked a housing and mortgage renewal boom. Buyers chased higher priced homes thanks to better monthly affordability, and many existing borrowers refinanced. Now those five-year term mortgages are up for renewal, and while rates have come down somewhat from their mid-2023 highs, those borrowers are looking at prime rates almost double their COVID-era lows. The question, then, is how mortgage holders can keep up.

Christine Tan is a Portfolio Manager with SLGI Asset Management Inc. She explained what we’ve seen so far among Canadians who entered into five-year mortgage terms in late 2020 and have already gone through the process of renewing at a higher rate. She outlined some of the macro forces now at work and explained how tightening consumer balance sheets could, or could not, impact Canadian markets. She stressed that as clients face higher carrying costs for their homes, the response from advisors may be to prioritize debt servicing over long-term savings, at least for now. She noted, too, that panic over rising delinquency rates may be overstated.

“If you look back to 2017 or 2019 before COVID, the delinquency rate for mortgages in Toronto was about 0.1 per cent. CMHC numbers project that by the end of 2026 Toronto could go as high as 0.4 per cent. That sounds high but if you look over the longer-term it’s actually returning to a longer-term normal,” Tan says. “It depends on how you frame things. You can frame it as increasing fivefold since 2022 and it sounds scary, but looking at the longer-term it looks more okay.”

While Tan acknowledges that this rise in delinquency rates is happening across the country and could impact as many as one million households, the broader context would point to this shift as very much something the Canadian economy can weather. Even though many markets are seeing home prices decline from their pandemic-era highs while debt servicing costs rise, this is all within bearable levels.

Drilling down somewhat, Tan sees this trend as another sign of the ‘K-shaped economy’ as well. She notes that lower income and first-time homebuyers are now facing harder to manage debt servicing costs. The impact of US tariffs will also play a role as major manufacturing cities in Southern Ontario, for example, are facing difficult renewals along with job losses.

While delinquency and default rates offer a more extreme view of mortgage cost impacts, Tan also explains how broad sentiment around costs have shifted. She notes that Bank of Canada survey data has found negative consumer sentiment for years now. That was initially sparked by high inflation before debt servicing costs started to be more acutely felt. Those debt servicing costs are now compounding existing consumer challenges around inflation and job instability. As a result, Tan says, consumers are putting off major purchases like homes and vehicles. That is happening despite broad income growth that’s matched or even outpaced inflation in recent years.

While the compounding impacts of inflation and economic insecurity make debt servicing an even more challenging issue for Canadians, Tan notes that there is some hope for those who invested in equities. Markets are at all time highs tight now and that appreciation might help offset a decline in net worth from property prices falling. It could also be a useful moment to take some profits to help pay down existing debt and make the mortgage renewal more bearable on a monthly basis. Advisors, however, have to have the conversation with their clients about how they can strike the balance between making today’s debt more manageable and investing for the future.

Tan acknowledges how difficult, nuanced, and individual the conversation about paying down debt or investing can be right now. She argues, though, that advisors can begin to manage that conversation by starting with a bird’s eye view. By looking at a client’s whole net worth, the capital market assumptions for their portfolio, the cost of their mortgage, and their time horizon an advisor can work out which levers need to be pulled, and by how much, to make the client’s financial picture make sense. At the same time, however, Tan acknowledges the emotional side of these decisions. She notes that issues of economic uncertainty and the relationship people have with their homes will all weigh on how clients manage these questions. Through it all, Tan says that she’s seeing advisors prioritize client wellbeing over everything else.

“The advisors that I’ve spoken to, they just recognize that we need to do what’s best for the client. And if it means in the short term, that their investment assets do draw down, that’s okay. Because the most important thing is to ensure that our clients come out on the other side of this,” Tan says. “At some point, rates will normalize again, and in fact, they are, because the worst of the rate shock will be cresting in early 2027. We’re getting to the worst of it now, and it’ll start to moderate as we get through the rest of this year.”

This article was written by David Kitai and is reposted from the Wealth Professional website.

26 Feb

Capital markets expected to drive Q1 bank earnings as loan growth lags

Latest News

Posted by: Dean Kimoto

Canadian banks are set to report first-quarter results that analysts expect will show an earnings boost from trading as well as muted loan growth amid a still-tepid housing market.

By Ian Bickis

Banks have been able to drive their earnings higher in recent quarters despite economic headwinds as their capital markets divisions have benefited from frothy stock markets and corporate activity.

The first quarter, which includes a bump from year-end trading, should continue the trend despite lower fee revenue in capital markets, said RBC analyst Darko Mihelic in a note.

He warned investors, however, that given the contrast between bank valuations and weaker Canadian economic data, any signs of slowing momentum could make further stock gains difficult.

“We suggest approaching the group with caution,” he said.

The weaker economic data includes home sales that have shown continued downward pressure.

The Canadian Real Estate Association says home sales in January fell 16.2% compared with a year earlier, and December sales were down 4.5% from the same month a year earlier.

The job picture has been mixed, with unemployment dropping in January because fewer people were looking for work, while the actual number of people with jobs fell by 25,000.

Overall, RBC expects the latest GDP figures to be released on Friday will show Canadian economic growth flatlined in the fourth quarter.

The trends have kept loan growth subdued at banks, but hasn’t become enough of a strain to significantly shift bank provisions for potentially bad loans.

Banks built up their provisions as interest rates rose and a wave of mortgage renewals heightened fears of a spike in defaults, but so far that hasn’t happened with delinquency rates still below long-term trends.

Provisions should continue with the trend, but any downward shift would be notable, said National Bank analyst Gabriel Dechaine.

“Although we don’t expect it, any changes to the credit outlook so soon after reiterating the base case of ‘improvement in the second half’ could hit sector valuation,” he said in a note.

Given the lack of loan growth, banks are instead devoting more capital to share buybacks, which not only boost stock prices but also the crucial earnings per share metric.

Overall, earnings coming in ahead of expectations in the first quarter could also boost the longer-term outlook for earnings per share, said Scotiabank analyst Mike Rizvanovic.

“We remain positive on the large Canadian banks heading into Q1 earnings season that we suspect will once again feature strong results in market-sensitive businesses, upside to all-bank margins … and credit losses remaining in a very manageable range.”

Scotiabank reports Tuesday, BMO Financial Group and National Bank of Canada are set to report their results on Wednesday while CIBC, TD Bank and Royal Bank of Canada are scheduled for Thursday.

This article is reposted from the Canadian Mortgage Trends website.

23 Feb

Residential Market Commentary – Winter Wallop for January Market

Latest News

Posted by: Dean Kimoto

The country’s housing market was stone cold in January and the Canadian Real Estate Association is blaming the weather – or at least the weather in parts of southern Ontario. Record setting snowfalls and ferociously cold temperatures appear to have kept house hunters indoors.

Seasonally adjusted sales were down nearly 6.0% in January compared to December. Still, more than 22,500 properties changed hands. The national average sales price slipped 2.6% compared to a year earlier.

CREA is not letting the weather cool its expectations for 2026 though. The Association is forecasting 5.1% sales growth and 2.8% price growth in 2026, driven by pent-up demand and a pent-up desire to sell. That desire to sell may be showing itself. New listings rose more than 7.0%, tipping the market further in favour of buyers.

There is a feeling among some realtors that, while the weather may have been a factor in January, the slump is a hold-over from the end of 2025. They say buyers, especially first-timers, are waiting for greater improvements in affordability through further price reductions and, perhaps, lower interest rates.

The latest inflation numbers suggest there may be some merit in that thinking. Statistics Canada reports headline inflation dipped to 2.3% in January, down from 2.4% in December. Most of the decline came from falling gasoline prices, but shelter inflation continues to slow as well. It dropped below 2.0% for the first time in five years. Hopes for lower interest rates seem more remote though. The Bank of Canada has been clear, it will not be moving rates unless there are very strong reasons to do so.

This article is reposted from First National Finacial’s Marketing Team.